

Today I sold my smallest holding, Eckert & Ziegler. I have held the stock for almost a year and added to it once shortly after buying on good news. Let’s quickly walk through my reasons and some reflections on fast gains.
Eckert & Ziegler is a German small cap with a focus on radioactive materials, isotopes. They mainly supply industrial, i.e. to calibrate highly accurate equipment or in O&G exploration, and medical clients. The business has a strong moat, driven by patents, infrastructure and know-how. I encourage you to read my deep dive into the company, here.
After spiking during the pandemic, EZ shares crashed and have still not recovered close to ATHs. I bought the company after they spun off their more speculative segment, Pentixapharm, which researched and developed radiopharmaceuticals. Pentixapharm had a much higher risk than the rest of EZ business.
After my buy in late 2024, shares performed really well, spiking soon after on raised FY24 guidance (when I bought my second tranche of shares). Within half a year the shares rose by 70% and have since then corrected down to a 37% gain since my first purchase.
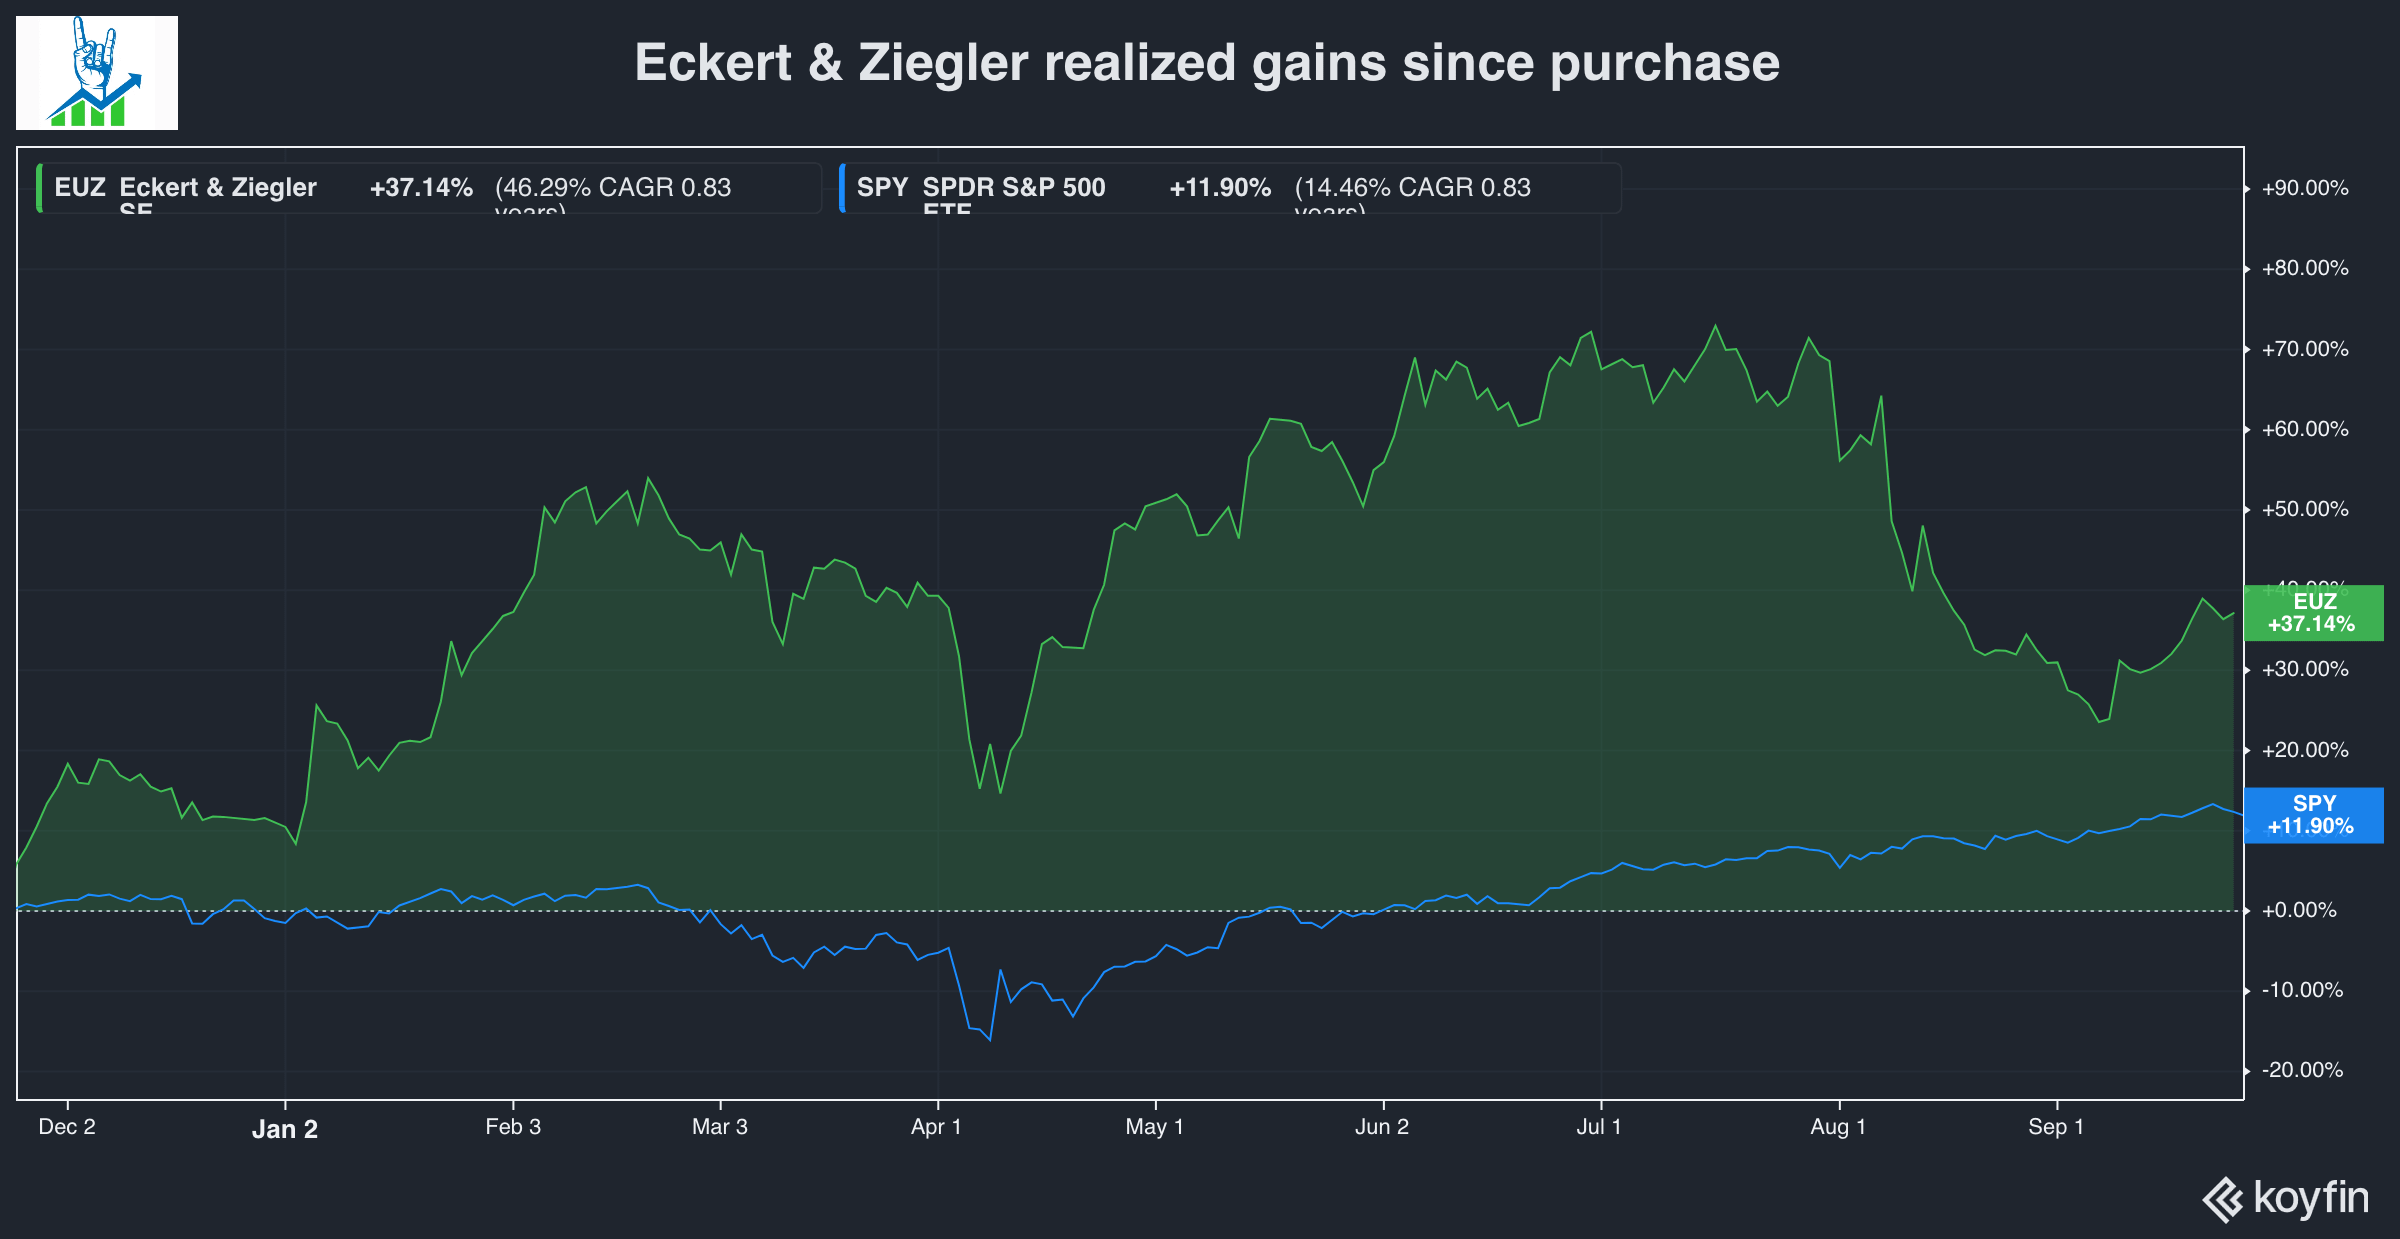
I sold today at a 20% gain on my full position. EZ probably will continue to do well over the long term, but here are the reasons why I decided to sell:
Small position size: At just 2% of my portfolio, EZ did not really matter. Two months ago I concluded that I want to cut small positions and focus on a more concentrated portfolio, so that my picks actually matter. You can read more on my reasoning here.
Valuation isn’t cheap: I asked myself a few times recently if I should increase my position, after shares corrected from their local highs. Going through the valuation (I’ll give my opinion on that later too) I noticed that I liked other opportunities more, based on a mix of quality and forward IRR. If I can’t buy more to make it a meaningful position, I might as well realize my gains.
It’s a hard business to understand: While researching the company, I learned a lot about its industry and it’s fascinating, but also highly complex. I always had a bit of a bad feeling because of this and never managed to gain a high conviction. Adding to my worries was that the founder focused on Pentixapharm following the spin. None of this was new information, but it always lingered in my mind.
Want Better Investing Tools? Get Exclusive Discounts on What I Use!
I rely on fantastic tools to research and track investments—you can too, at a discount:
🔹 Koyfin – 20% off + 7-day free trial (my main research tool) Check my showcase of Koyfin’s latest fantastic feature here.
🔹 Finchat – 15% off (unique data visualization & KPIs)
🔹 Portseido – 20% off (portfolio tracking & return calculations)
🚀 Upgrade your toolkit today!
Valuation
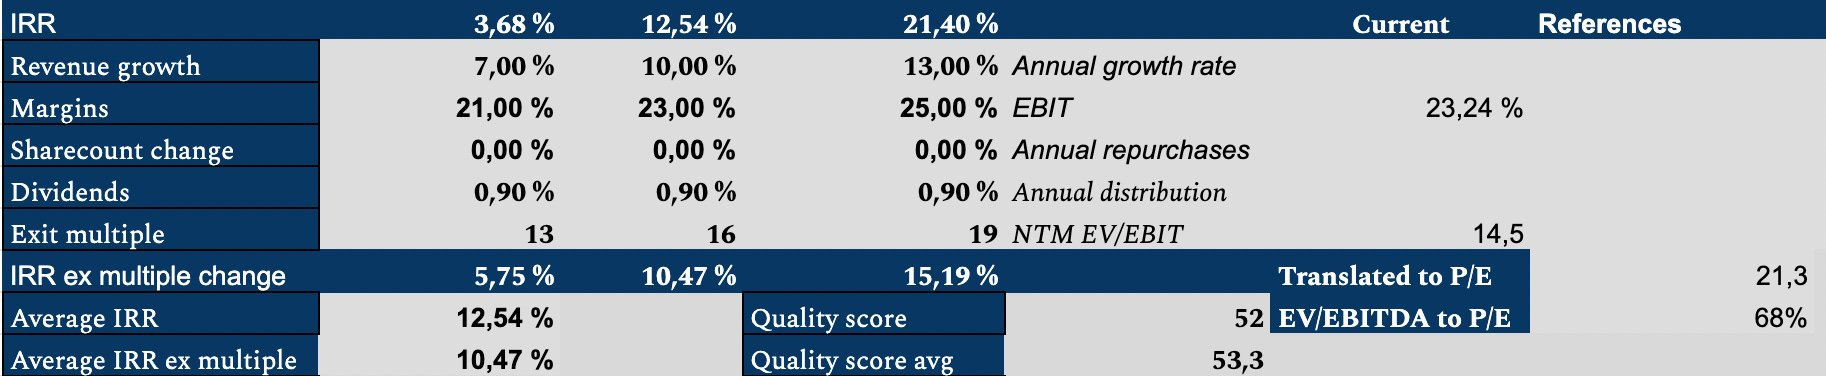
Eckert & Ziegler has a decent projected IRR, but that relies on relatively high growth rates. The company has good secular tailwinds from radiopharmaceuticals, but the rest of the business is growing slower. As mentioned earlier, it’s a hard business to understand and I’d appreciate it if management was clearer on their longer term targets and expectations. I am not as confident in my projections with this company as I usually am. Check out this post for a deeper dive into its valuation and growth drivers.
When buying EZ the valuation was cheap enough to buy it, but since then I raised my hurdle rate and expect a better IRR, especially if I don’t fully understand the company.
I’d not be surprised if I check back in on EZ in a few years and see that the share price is materially higher, but I see better risk-adjusted returns elsewhere. I’ll keep the company on my watchlist.
What annoyed me, in hindsight, is that I did not sell some shares, despite acknowledging that the price was not cheap anymore after its 70% run. Given my limited conviction and not fully understanding the business, it would’ve made sense to take my gains back then. Going forward, I want to be quicker in trimming in situations like this. Over the last 5 years, I’ve seen too many instances of my winners walking back their gains. Often I acknowledged that shares were overvalued and never got myself to trim. Let’s see if I’ll have success doing that!