

On November 4th, Edenred unveiled its new strategic framework, Amplified 25-28 at its Capital Markets Day in Paris. The company’s tone was confident. With 70% of revenue now coming from markets where Edenred is already the #1 player, it’s shifting focus from territorial expansion to scaling existing platforms and monetizing more of its high-engagement ecosystem.
Edenred has seen continuous multiple contraction over the regulatory risks looming over its business. If we drill down however we see a highly diversified business across geographies and segments. The regulated business is only the Meal & Food (pink) business, accounting for around 41% of revenue. While this is a lot, it’s also very diversified.
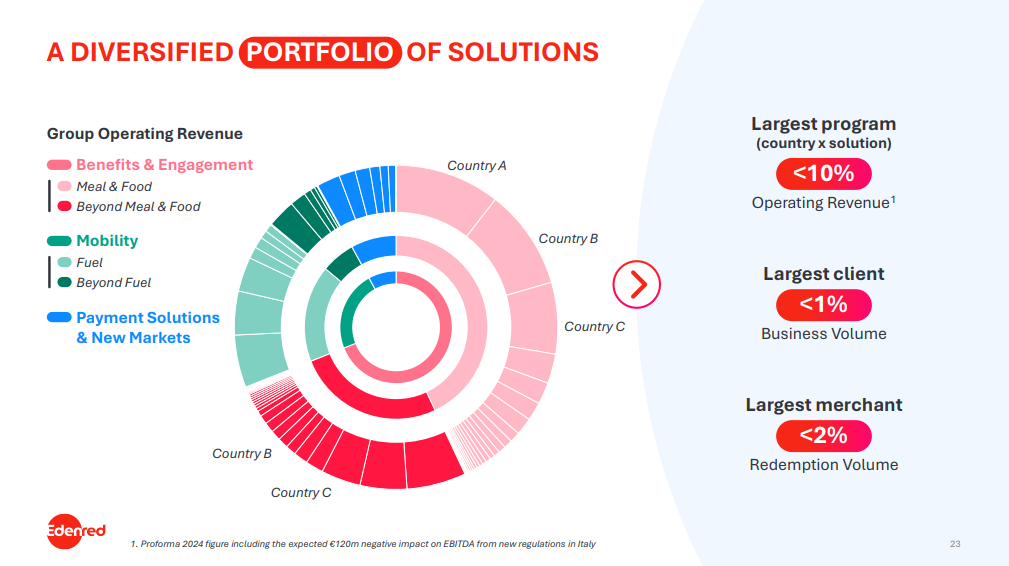
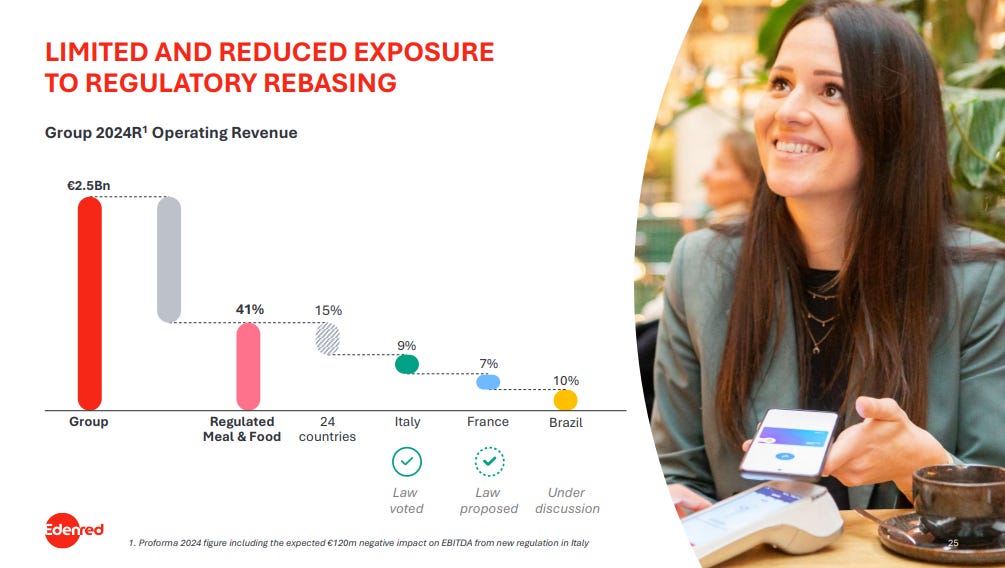
We can see that Edenred operates in 27 countries. The issue lies in their three core markets:
Italy (9% of operating revenue): Lay already voted and impact is already in the PnL and guidance. This is offset by a 25% increase in the face value cap in 2026.
France (7%): Laws are proposed, but partially opposed by all parties. The Meal voucher reform overall is seen as favorable for Edenred, as it forces the full digitization of the industry over time.
Brazil (10%): The largest market and a source of uncertainty.
24 Countries (15% of operating revenue): Continues to operate and receive regular increases in the legal face value cap in many countries. Increases in face value make Edenred a direct beneficiary of inflation.
Within the Meal & Food segment revenue is further diversified between:
Retail (50%): Small retail (e.g. grocery or bakeries) to large retailers.
Restaurants (25%) in all sizes.
E-Commerce (25%).
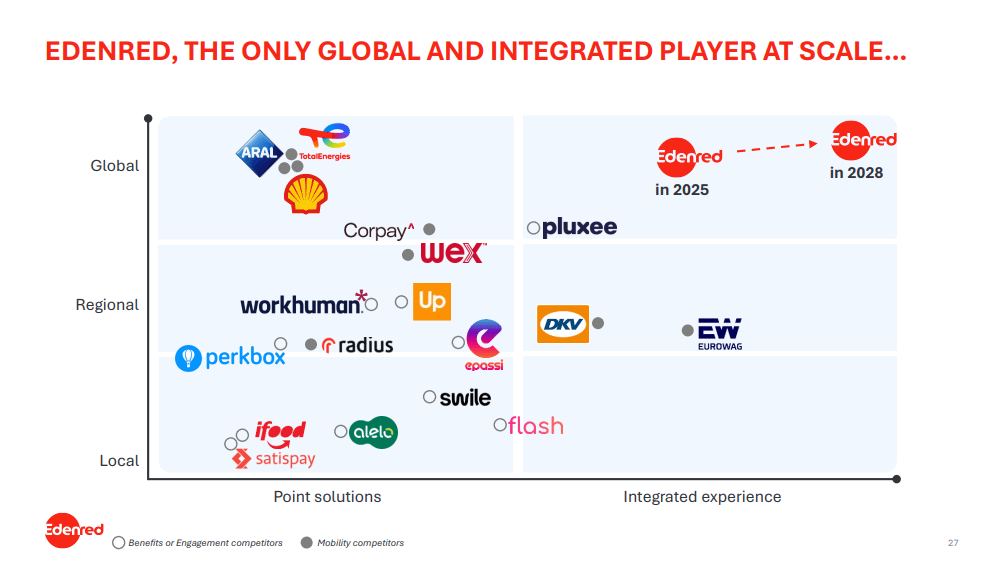
Below we can see a comparison between Edenred and its peers. The only comparable rival is Pluxee, operating on a global scale, but only in the Benefit and Engagement segment. No other company combines a wholistic platform between employee benefits and mobility solutions.
The global Meal & Food opportunity is still large, with most geographies under 35% penetrated. Brazil (55% penetrated), Italy (34%), France (30% and Turkey (30%) are leading in adoption, but even here are large white spaces. Especially SMEs have much lower penetration, i.e. in Brazil (20%), France (10%) and Italy (5%) compared to the market. SME’s thus as a focus for Edenred’s marketing efforts (as well as rival Pluxee’s).
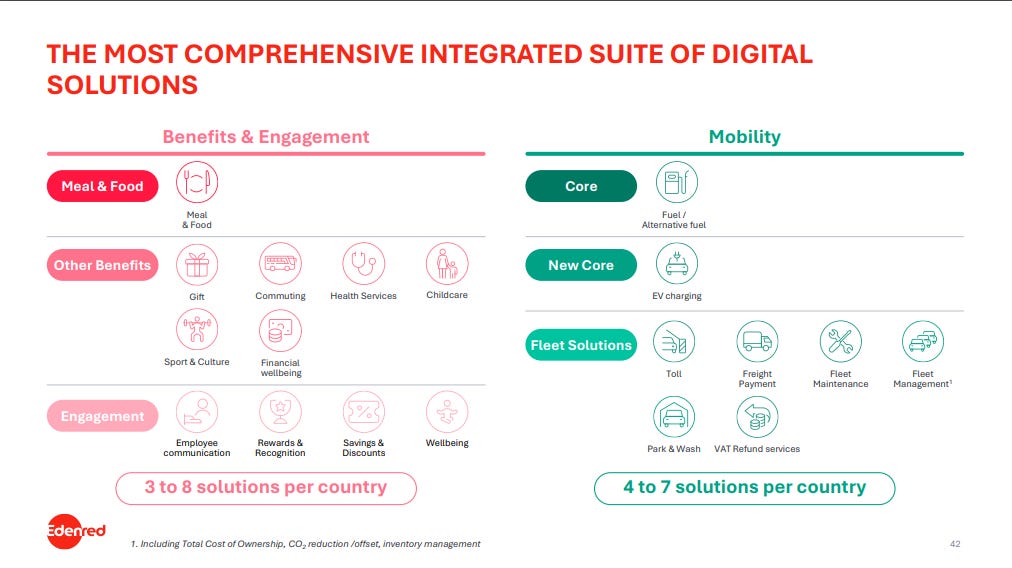
All of these services are integrated into one platform, enabling strong cross- and up-sell potential. No competitor can offer a similar breadth of offering than Edenred. On top of this, there are also the Payment Solutions & New Markets solutions that can be cross sold.
Technology investments
Edenred pointed out its PayTech platform and claims to be the only player processing payments internally, creating a 10% price advantage versus competitors. The results are greater control over innovation, scalability across its 100+ payment schemes and best-in-class up times (99.99%).
This internal infrastructure allows Edenred to ship fast, with 13 new features per week, and to iterate product experiences in a way few traditional issuers or aggregators can match.
Notably, Edenred plans to invest €1.8B in technology through Amplified, with AI spending increasing 6x versus the 2024 baseline. Management claims this has already improved product development speed by 15%, and expects further acceleration as AI tools mature. 10% of tech spend will go towards security spending.
The road to 5€ billion
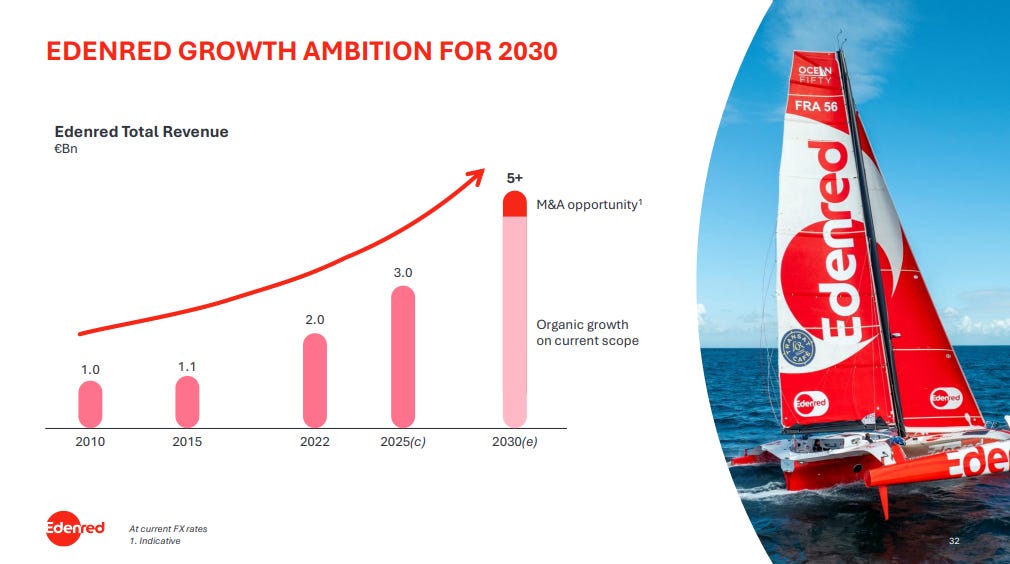
Edenred has stuck to its 2030 target of 5€ billion in revenues, now with a higher contribution from organic revenue growth. Management also reiterated that they will do bolt-on deals if they present themselves, but no larger deals. If there’s a gap in their offering they are fine enhancing their platform, but now they can grow organically within their end-to-end solution.
I like that, as overpaying for some deals (like Reward Gateway) has been a bear case for Edenred. After all, what’s the value of FCF if it is spent on expensive M&A? Fortunately, Edenred has massively improved their capital allocation over the last year, focusing on returning capital with its large dividend and buybacks at these attractive levels, while still investing for organic growth.
What’s next?
Edenred has set some ambitious growth targets, expecting over 5€ billion in revenue by 2030. But how are they going to achieve this? How advantaged is this business really why am I getting increasingly bullish on its transformation?
In the next sections we dive deeper into the highlights of the CMD and my take on the current valuation.