

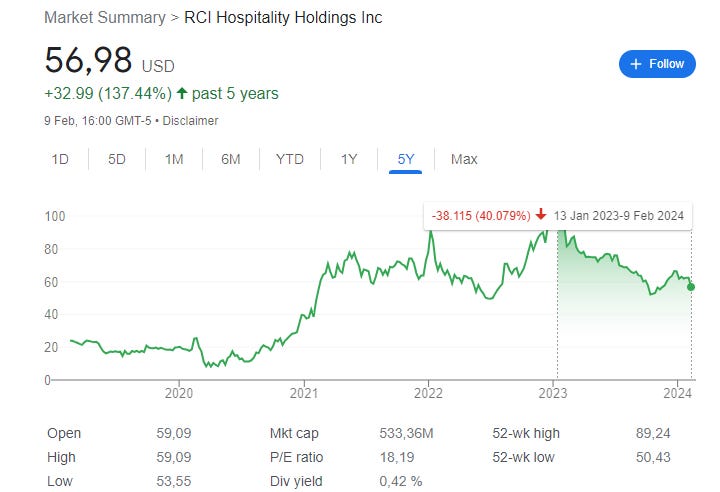
RCI Hospitality, more commonly known as RICK 0.00%↑, has had a tough year. After the COVID sell-off, the company ran up 800% but has since fallen 40%. Last week's quarterly report sent the stock down 6%, and deservedly so. Let’s dive into the report, why it was so bad and if I consider selling my stake in the company.
RICK is the only publicly traded night/strip club operator on the market. The industry is fragmented and anti-ESG, with limited interested buyers. As the largest player and the only one who can raise money as a public company, RICK is a preferred buyer in this industry. Because municipalities don’t want new clubs, the existing ones have an intrinsic moat in their (often grandfathered) licenses. I plan to publish a deep dive into the business model and fundamentals in the coming months, so I won’t get too deep into the business's competitive advantages.
Earnings
Results came in well below expectations: EPS was expected to come in at $1.04 but instead was $0.87; this represents a 27% decline Y/Y. While I usually don’t look too much at analyst expectations, RICK really disappointed here (and not just at EPS). Revenue was in line with expectations and grew 5.6%. This revenue growth was attributed to newly acquired clubs, offsetting a 9.8% decline in same-store sales (SSS).
While the clubs saw an 8% SSS decline, the same as the last quarter (but still way better than privately owned peers shrinking 20%+ allegedly), the Bombshells “Breastaurant” division saw an acceleration of decline from 14% SSS to 20% SSS decline! Operating income for Bombshells completely collapsed in the quarter, dropping from 8.7% last quarter to 0.7%!
Operating Cash Flow was more stable, declining just 9%, but this was mainly attributable to net working capital changes (check out my recent post talking about NWC and other issues of Operating/Free Cash Flow).
Overall earnings were bad and continued a worrying trend of operating decline over the last few quarters. Besides the operational worries, I wouldn’t say I like that the casino venture will be a big part of the business because I do not like gambling from an ethical point of view. This, however, is a personal issue and has nothing to do with the investment case. Let’s dive deeper into the results.