

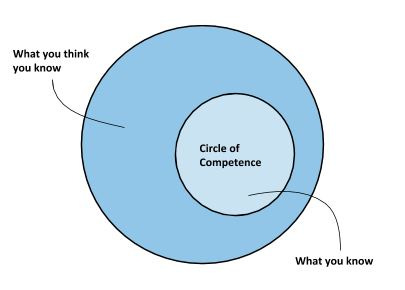
Last week I was at a Value investor meet up in Vienna, organized by Andy/EVFCFAddict. During the event I talked with investors that have more experience with the Oil & Gas industry about Ashtead Technology and it has made me revisit the investment case. In this post I want to address some oversights I had, different ways to look at the industry and the importance of a circle of competence.
What’s Ashtead Technology?
Ashtead Technology (AT) is a UK based equipment rental business focused on subsea equipment for the offshore Oil & Gas (75% of sales) and renewables (25%) industry. The business is similar to Ashtead Group and I wrote a comparison piece here. Equipment rental businesses have great unit economics and AT can rent out its fleet for 12 years on average before they need to be discarded.
Currently, Ashtead is a top 5 position within my portfolio. After talking to people that are experienced with this industry I have to admit that it’s tough to understand the O&G market as a tourist, a generalist that just visits the space. I found a few errors in my judgment that led me to reduce the exposure to this company significantly. Let’s look at these errors and how they effect my quality and IRR scores:
Cyclicality: Currently, its customers are reporting strong backlogs of planned projects, but in a highly cyclical industry these projects can be delayed or cancelled. It is some visibility, but not a certainty. Furthermore, equipment rentals are usually assigned on a very short term basis to those projects, so Ashtead might not fully benefit from them.
2015-2016 subsea collapse: AT was not public during the last cycle bottom, but even resilient subsea contractors with strong balance sheets saw backlogs reduced, revenues down by 30-50% and margins collapsing. Limited public history during a pretty good time for the sector distracts from the inherent cyclicality of the industry. High utilization could be a sign of the cycle instead of a structural competitive advantage.
Recurring revenue from maintenance and inspection: In theory a strong portion of recurring revenue from M&I revenues should make AT more resilient, but the reality in O&G is that these oil rigs can work quite a while before they need maintenance work done, if companies are strapped for cash in a down cycle.
Peter Lynch: One of the greatest fund managers of all time famously explained that investing in cyclicals works differently than normal companies. We should buy those at high multiples, when they are going through trouble (assuming they won’t break under a heavy debt burden). Low valuation multiples often are seen during cyclical peaks. Ashtead Technology could be one of those cases, trading at a cheap 6.7x forward EV/EBIT.
Capital allocation in a cyclical industry: AT does everything right if we benchmark it as a non cyclical company. They reinvest everything into growth at high ROIC, creating strong incremental returns on capital. But in a cylical industry overbuilding can have a strong negative effect. They have their fixed cost base from their assets and lower utilization and pricing can crush margins, potentially even pushing them down towards becoming unprofitable. That’s why many O&G investors seek high dividends to get the capital out and reduce risk. For an industry like this a less aggressive expansion might be a good thing.
Overall, I think I can say that I overestimated my circle of competence and that I shouldn’t have averaged down so much on it. The thesis might still work, but it’s not a risk and reward profile I want to have as a core position in my portfolio. Let’s take a look at how this impacted my quality score and IRR model.